Appraisal News and Business Tips

Blog

About this blog

This blog has all my free weekly email newsletters since 2012. Plus other topics. Please note that the original email newsletter subject line has been significantly shortened. To see the original email newsletters, click here to go to the newsletter archives. The newsletter has been sent out weekly since June, 1994. To subscribe to the free email newsletters and receive them on the date they are first issued, go to www.appraisaltoday.com and sign up in the big Yellow Box!!

NOTE: All newsletters before 4/6/24 do not have the popular Liability Administrator ad in the top of the newsletter post.
Starting with the 4/6/24 newsletter it is added below the top topic.
The 30 most recent newsletters (with the LIA ad) are available in the newsletter archives at https://appraisaltoday.com/archives/
The most recent 30 appraiser newsletters start with Newz: the other emails on the list are ads.

Looking for a topic? Use Search box on the right side. There are hundreds of posts on this blog, starting in 2012. 

Every week I send out my FREE email newsletter with info on strange and weird homes and buildings, what Fannie, FHA, AMCs, UAPAP, etc. Hot topics important to appraisers. See info on the right column for topics.

I have also been publishing a paid Appraisal Today monthly newsletter since June, 1992 with in-depth articles on topics important to appraisers. This newsletter has detailed articles on appraisal topics such as Adjustments and Collateral Underwriter plus business topics such as fees, marketing tips, and productivity to get more appraisals done. Click below for more info!!

What’s the difference between the Appraisal Today free weekly email newsletters in this blog and the paid monthly newsletter?(Opens in a new browser tab)

FREE email newsletter FAQs(Opens in a new browser tab)

Posted in: Uncategorized

AMC Panel Requirements

Newz: UAD 3.6: Fees, Turn-Time, Software and more, AMC Panel Requirements

October 30, 2026

ARTICLE LIST – In order, scroll down the page to read

  • LIA AD: AMC Panel Requirements
  • UAD 3.6: Inside the Struggle Over Fees, Turn-Time and Software By Frank Andorka, Managing Editor WorkingRE
  • A Clifftop Compound With 2 Brand-New Cabins in Idaho Hits the Market
  • What is Highest and Best Use in Appraisal? (Updated for UAD 3.6) , By Kevin Hecht
  • MY AD: What Enough of UAD 3.6, I Have a Business to Run!, By Doug Smith, MBA, SRA
  • UAD 3.6: A New Era of Accountability in Appraisal Quality, By Gynell Vestal (Administrator) American Valuation Society
  • Flock Camera Blunders and the Privacy Risks of UAD 3.6, By Desiree Mehbod
  • MBA stats: Mortgage applications increased 3.4 percent from one week earlier
 

Thanks to our Sponsor!!

——————————-————————-

UAD 3.6: Inside the Struggle Over Fees, Turn-Time, Software and more

By Frank Andorka, Managing Editor, Working RE

Excerpts: Editor’s Note: Since this article was written, the GSEs created an exception to UAD 3.6 implementation for sellers who aren’t able to make the full transition to the new standard before Nov. 2. The exception runs through May 19, 2027. The GSEs will also allow resubmissions of UAD 2.6 appraisal reports through June 27, 2027. As of March 1, 2027, UAD 2.6 appraisals will no longer qualify for certain appraisal-related representations and warranties relief. For more, check out our full report at workingre.com:

GSEs Create Exception for UAD 3.6 Deadline: Runs through May 19, 2027.

To read: Click Here

Nov. 2 is usually just another day on the calendar — but not this year

Timeline and Rollout

The rollout of UAD 3.6 has been hampered considerably by two problems: slow software rollouts and lenders dragging their feet. When Working RE covered Valuation Expo in Las Vegas at the end of August, the problems clearly came into view.

While most of the leading software providers received initial approval from the GSEs in late 2025 and early 2026, word on the ground at Valuation Expo (Val Expo) was that there were still plenty of bugs to work out. AMC executives privately shared that they had staff simultaneously testing all the GSE-approved reporting software so they could troubleshoot and support appraisers when they inevitably ran into problems trying to turn in assignments. Some of those bugs were being run back to the software companies in real time, with the appraiser, AMC, lender and software provider working through the problem together.

The bigger problem in August was that lenders had barely begun ordering the 3.6 appraisals at all. Rocket Mortgage staff at Val Expo said they had ordered six UAD 3.6 appraisals. Rocket originates roughly six to seven percent of all residential mortgages in the United States. Several regional AMCs reported completing exactly two assignments apiece — and in each case, one of the two was a test run the AMC had ordered itself.

Scott Reuter, chief appraiser at Freddie Mac, summed up the bind on a panel at the show: “Appraisers cannot do a 3.6 assignment unless somebody orders a 3.6 assignment.”

More Than 900 Data Elements

There were approximately 190 data elements in UAD 2.6. There are now more than 900 in UAD 3.6. Reuter says it’s easy to be overwhelmed if appraisers just hear the number, but he assures the industry that appraisers were in the room when the form was developed.

“I want to make sure they don’t just hear ‘more than 900 elements’ and worry that they won’t be able to do it,” Reuter says. “They won’t have to fill out all those data points for every property. They are never going to touch the lion’s share of them, but we wanted to make sure we accounted for every potential contingency just in case.”

Lyle Radke, senior director of collateral policy at Fannie Mae, says Fannie and Freddie hold, between the two of them, $7 trillion in mortgage debt which, since it’s backed by the U.S. Treasury, is guaranteed by U.S. taxpayers. Therefore, it stands to reason collecting more data than before is important.

“From that perspective, the data is essential,” Radke says. “It’s how we manage risk. UAD 3.6 makes it easier for us to see and understand the data. If we didn’t have 3.6, we could still parse the data, but it would be much more challenging and time consuming.”

Other topics include turn times, liability and fees.

As the industry rushes toward the Nov. 2 deadline, appraisers’ stress levels will continue to rise. The only question is: What will things look like when the smoke clears? Only time will tell.

To read more, Click Here

My comments: Good discussion of the issues with quotes from many people, including GSEs. Not many changes since the August conference, except software vendors are still sending out updates. Fees still unclear.

——————————————————–
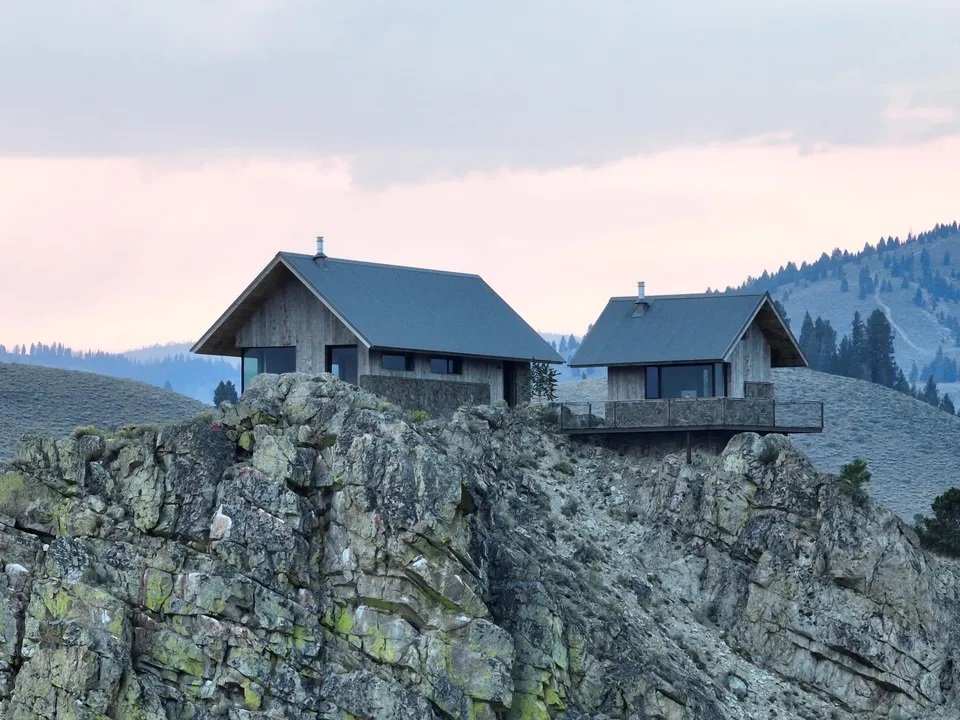
A Clifftop Compound With 2 Brand-New Cabins in Idaho Hits the Market for $2,299,000

Excerpts: 1 bedroom, 1 bath, 306 sq.ft., 3.06 Acre lot, Built in 2026

It’s all about location, location, location for two newly built mountain cabins perched atop a cliff outcropping in Idaho that have just hit the market.

Located on 3.06 acres in Stanley, where “snowmobiling, hiking, and mountain biking adventures begin right outside your door,” The sleek residences are surrounded by sweeping views of the Stanley Basin, the Sawtooth Mountains, Valley Creek, and the Salmon River. They come with “direct access to vast stretches of surrounding wilderness.”

A primary 900-square-foot cabin features a vaulted wood ceiling, wood-burning stove, heated flooring, modern kitchen, full bathroom, and sleeping loft.

The secondary structure has a loft and wraparound deck. It also offers flexible space that could be used for guest accommodations, a studio, home office, or fitness center.

Just minutes from downtown Stanley, the gated property also borders 465,000 acres of National Forest land.

To see the listing with 45 photos and an aerial view, Click Here

——————————————————–

What Is Highest and Best Use in Appraisal? (Updated for UAD 3.6)

By Kevin Hecht

Excerpts: What’s New: Fannie Mae’s HBU Policy Under UAD 3.6

For residential appraisers, highest and best use is more than a valuation concept. It is also a GSE eligibility requirement, and in September 2026, Fannie Mae changed it.

In Selling Guide Announcement SEL-2026-08, Fannie Mae updated its HBU policy for appraisals completed on the redesigned Uniform Residential Appraisal Report (URAR) under Uniform Appraisal Dataset (UAD) 3.6.

What Changed

Residential use, not present use. Under the prior guidance, the present use of the property generally had to be its highest and best use. Now the property’s HBU, as improved or as proposed, must be a residential use. It no longer has to be the present use.

Primarily residential 1-4 unit properties. The property must be primarily a one- to four-unit residential property, and any non-residential use must be subordinate to the residential use. This replaces the earlier “residential in nature” standard. Fannie Mae’s UAD 3.6 Policy Supplement defines present use, residential use, and subordinate use for this purpose.

A path for properties that fail an HBU test. The update sets eligibility criteria and reporting requirements for one- to four-unit residential properties whose present use fails one or more of the four HBU tests.

When It Applies

The policy applies to appraisals completed on UAD 3.6. It does not apply to appraisals completed on the legacy forms. As of November 2, 2026, UAD 3.6 is required for new submissions to the Uniform Collateral Data Portal (UCDP), so most Fannie Mae appraisals now fall under the new policy.

Some lenders have more time. Under a temporary exception announced September 30, 2026, approved sellers that requested it from Fannie Mae or Freddie Mac can keep submitting UAD 2.6 appraisals on the legacy forms through May 19, 2027. UAD 3.6 becomes mandatory for everyone on May 20, 2027. Until then, you may get assignments in both formats. The new HBU policy applies only to UAD 3.6 reports, so confirm your client’s UAD requirements before you accept an assignment.

Freddie Mac has not made the same HBU change. As of its September 2026 guide update, Freddie Mac still requires the present use to be the highest and best use. Because the two GSEs now differ, confirm with your client which guidelines apply when the present use is not the HBU.

What It Means in Practice

Consider an older single-family home on a lot that was recently rezoned for townhomes. The existing house may no longer be the maximally productive use of the site. Under the old approach, that conflict could raise an eligibility problem. Under UAD 3.6, the HBU is still residential, so the property may remain eligible if it meets Fannie Mae’s criteria and the appraisal reports the analysis as required.

The redesigned URAR also puts more weight on narrative, evidence-based support for the HBU conclusion than the legacy forms did. Be ready to explain why the market supports a residential use, whether any non-residential use (such as a home-based business or agricultural outbuildings) is subordinate, and, when the present use fails a test, which test it fails and why.

For exact definitions and reporting requirements, read the UAD 3.6 Policy Supplement.

Topics also included:

Many general HBU topics.

Survey: What’s the Most Common Error Appraisers Make When Performing an HBU Analysis?

To read more, Click Here

My comments: THIS IS A SIGNIFICANT HBU CHANGE ONLY FOR UAD 3.6!

My November 2026 Appraisal Today issue has a long article about Fannie’s HBU changes written by Denis Desaix, MAI, SRA, a HBU expert.

After reading Denis’ detailed article, I had difficulty understanding what has changed and what it means. The Playbook (below) helped me significantly.

Be sure to read these documents:

MOST IMPORTANT DOCUMENT

The Highest and Best Use Playbook – An excellent presentation of the “big picture” for this New HBU requirement for UAD 3.6

https://singlefamily.fanniemae.com/media/47851/display

—————-

Highest and Best Use Frequently Asked Questions

https://singlefamily.fanniemae.com/media/48061/display

—————————————————————–

UAD 3.6 Policy Supplement

https://singlefamily.fanniemae.com/media/42571/display

—————————————————————-

Why did Fannie do this?

To make more properties eligible for Fannie mortgage loans. No more clicking the NO box for conforms to HBU requirements. UAD 3.6 does not have a No box. Today, in many areas, there are few homes available for purchase with high prices.

——————————————————–

Are you getting too many ad-only emails?

4 ways to get only the FREE email newsletters and NOT the ad-only emails.

1. Twitter: https://twitter.com/appraisaltoday posted by noon Friday – all recent newsletters

2. Read on blog www.appraisaltoday.com/blog Posted by noon Friday. You can subscribe to the blog in the upper right of each blog page.

3. Email Archives: https://appraisaltoday.com/archives

(posted by noon Friday) The link is above and to the right of the big yellow email signup form. Newsletters start with “Newz.” Contains all recent emails sent.

4. Link to the 10 most recent newsletters (no ads) at www.appraisaltoday.com. Scroll down past the big yellow signup block.

To read more about the 4 ways, plus information on why I take ads, etc. Click here

——————————————————–

Enough of UAD 3.6, I Have a Business to Run!

Revenue Strategy: Managing the Business (Part 1)

By Doug Smith, MBA, SRA

In the November 1, 2026 issue of Appraisal Today

Excerpts:

“A time of turbulence is a dangerous time, but its greatest danger is a temptation to deny reality.” – Peter F. Drucker

The transition to UAD 3.6 is proving to be one of the most disruptive

changes many appraisers have experienced in their professional careers.

What initially appeared to be a change in reporting requirements has become a far more extensive transformation of the appraisal process.

Established workflows are being reconsidered. Familiar software

procedures are changing. New equipment, training, and additional expenditures may be required. Even experienced appraisers are discovering that the time and effort needed to complete an assignment may no longer resemble what they have come to expect.

The full economic consequences remain uncertain. But one thing is

becoming clear: That realization presents an opportunity.

Rather than concentrating exclusively on adapting our reports, perhaps this

is the appropriate time to reconsider something more fundamental: What do we want from our careers as professional appraisers?

Peter Drucker encouraged organizations to begin with a fundamental

question: What is our mission?

For appraisers, the answer must recognize our responsibility to the public

trust. Our work supports decisions by people and institutions relying on credible opinions of value. Our professional obligations extend beyond satisfying the company ordering the appraisal.

We are appraisers. Our responsibility is to analyze real estate markets,

interpret market evidence, and develop credible opinions of value.

Our primary purpose is not to make a software program work.

To read more about this topic in Part 2, plus 2+ years of previous issues, subscribe to the paid Appraisal Today.

If this article helped you understand your business better, it is worth the subscription price!

—————————————————————-

Not sure if you want to subscribe?

Sign up for monthly auto renewal for $8.25!

Cancel at any time for any reason!

You will receive a prorated refund.

$8.25 per month, $24.75 per quarter, and $89 per year (Best Buy)

or $99 per year or $169 for two years

Subscribers get FREE: past 18+ months of past newsletters

To purchase the Monthly Appraisal Today newsletter:

www.appraisaltoday.com/order or call 510-865-8041

What’s the difference between the Appraisal Today free Weekly email newsletters and the paid Monthly newsletter? Click here for more info

Cancel at any time for any reason!

You will receive a prorated refund.

$8.25 per month, $24.75 per quarter, and $89 per year (Best Buy)

or $99 per year or $169 for two years

Subscribers get FREE: past 18+ months of past newsletters

To purchase the Monthly Appraisal Today newsletter:

www.appraisaltoday.com/order or call 510-865-8041

——————————————————–

UAD 3.6: A New Era of Accountability in Appraisal Quality

October 26, 2026

By Gynell Vestal (Administrator) American Valuation Society

How standardized appraisal data could transform secondary market risk management, lender oversight, and the future of appraisal development.

Excerpts: What happens when the secondary mortgage market can evaluate appraisal quality with a level of consistency, transparency, and sophistication that wasn’t previously possible at scale?

I believe this is where UAD 3.6 has the potential to fundamentally change the valuation industry.

Not simply by changing how appraisals are reported, but by creating greater accountability throughout the entire valuation process, from the secondary market to lenders, AMCs, and ultimately the appraiser developing the opinion of value.

The Real Significance of Standardized Appraisal Data

UAD 3.6 is fundamentally a reporting standard. It doesn’t change the principles of appraisal development or the appraiser’s responsibility to produce a credible opinion of value.

What it changes is how appraisal information is structured, communicated, and made available for analysis.

Historically, appraisal reports have contained a significant amount of narrative information, often presented with varying levels of detail and consistency. While lenders and secondary market participants have long employed automated collateral review tools, the limitations of legacy reporting formats have constrained how comprehensively certain appraisal information can be analyzed across large volumes of reports.

UAD 3.6 introduces a more structured, standardized dataset that creates opportunities for increasingly sophisticated automated analysis.

And that has implications far beyond the appraiser’s reporting software.

Structured data can make it easier to identify inconsistencies, evaluate reported property characteristics, compare appraisal information against external datasets, and flag potential deficiencies for further review.

As analytical technology and artificial intelligence continue to advance, these capabilities can become even more powerful.

But the real significance isn’t simply that more appraisal data can be analyzed.

It’s who can analyze it, how consistently it can be evaluated, and what happens when weaknesses are identified.

The Secondary Market: Where Accountability Begins

Consider the implications for the government-sponsored enterprises and other secondary mortgage market participants.

Their exposure to collateral risk makes the quality of the underlying appraisal an important component of mortgage risk management.

With more standardized and machine-readable appraisal data, secondary market participants have an opportunity to enhance their existing review systems, develop more sophisticated risk indicators, and identify potential appraisal deficiencies with greater consistency.

Rather than relying primarily on individual report reviews or limited automated checks, increasingly advanced analytical systems can evaluate patterns across large volumes of appraisal data.

Additional topics

  • The Accountability Effect: From Secondary Market to Lender
  • As the secondary market becomes better equipped to evaluate valuation risk, lenders have a stronger incentive to strengthen the quality-control processes that identify and address those risks before loan delivery.
  • That accountability will naturally extend to the valuation service providers supporting those lenders.

What This Means for AMCs and Appraiser Performance

A Changing Landscape for Appraiser Panels

There’s another development worth considering, particularly from the lender and AMC side.

UAD 3.6 is already creating opportunities for appraisers who prepared early for the transition.

We Cannot Simply 2.6 the 3.6

I’ve been thinking about this distinction between reporting and development for some time.

UAD 3.6 changes the way appraisal information is reported, but the principles of credible appraisal development remain the same.

Appraisers must still identify and analyze relevant market data, select appropriate comparable properties, develop supportable adjustments, and reconcile their findings into credible opinions of value.

Better Data Must Lead to Better Quality Control

The Next Chapter of Appraisal Quality

The secondary market can use standardized data to strengthen valuation risk analysis. That creates greater accountability for lenders, which in turn creates stronger incentives for meaningful appraisal quality control and AMC oversight. Ultimately, those expectations reach the appraiser and the quality of the underlying appraisal development.

This accountability already exists in various forms. UAD 3.6 creates an opportunity to make it more consistent, more data-driven, and potentially more effective.

The real promise of UAD 3.6 isn’t simply a more modern appraisal report.

It’s the possibility of a valuation ecosystem in which better data supports better risk management, stronger accountability, and greater recognition of credible appraisal development.

That’s the opportunity I believe the industry should be preparing for.

To read more, Click Here

My comments Definitely worth reading. I had never read about this topic or even knew about the topic. Appraisers often forget about the lender side of UAD 3.6 and all lender appraisals.

——————————————————–
Flock Camera Blunders and the Privacy Risks of UAD 3.6

By Desiree Mehbod

A shocking Flock camera mistake triggered a midnight police raid on an innocent mother, exposing the dangerous reality of automated data overreach heading our way under UAD 3.6.

Excerpts: The Richmond police department just handed real estate appraisers the ultimate warning story about the dangers of automated data and algorithmic overreach. On July 29th, just before two in the morning, Richmond police officers woke up Rosalyn Crump, a mother of three, and towed her 2012 Hyundai Elantra right out of her driveway over a shooting she had absolutely nothing to do with.

The justification for this midnight raid was a hit from a Flock safety license plate reader camera. Body camera footage later revealed that officers walked up to the car, shined flashlights through the glass, and noticed children’s car seats buckled into the back.

The homeowner came outside and explicitly told the officers they had the wrong car, explaining her exact timeline for the day and the fact that the vehicle had been sitting idle. Instead of using human logic, looking at the physical evidence, or listening to the homeowner, an officer decided her story did not match the machine’s data and declared on camera that she was definitely not telling the truth.

We are watching a dangerous cultural shift where institutional systems place blind faith in digital data repositories while completely discarding human expertise and physical reality. In the Richmond towing case, a computer screen told an officer that a vehicle was involved in a crime, and that digital output instantly overrode the physical presence of children’s car seats and a mother’s direct testimony.

Appraisers are being forced into a parallel trap under the new UAD 3.6 data demands. Fannie Mae and Freddie Mac are demanding that we sweep through private residential spaces, capturing high-resolution interior photographs of bedrooms, living areas, hallways, and security setups, and then funnel that data into centralized, standardized databases accessible to unknown third parties.

When appraisers object to signing Certification 25, which strips away our core confidentiality defense and allows this private property data to be aggregated, corporate pragmatists tell us we are being dramatic. They claim the data is secure and meant only for secondary market functions.

But the Richmond incident proves that once a massive, standardized digital database exists, it will inevitably be hooked up to automated scanning tools and surveillance networks.

To read more, and watch the video of the encounter (near the bottom of the article)

To read more, Click Here

My comments: Worth reading. I had never thought (or read about) this aspect of UAD 3.6 increased data availability. Scary.HOW TO USE THE NUMBERS BELOW. Appraisals are ordered after the loan application. These numbers tell you the future for the next few weeks. For more information on how they are compiled, click here.

Note: I publish a graph of this data every month in my paid monthly newsletter, Appraisal Today. For more information or get a FREE sample go to www.appraisaltoday.com/order Or call 510-865-8041, MTW, 7 AM to noon, Pacific time.

My comments: Rates are going up and down in 2026.

—————————————————————————

Mortgage applications increased 3.4 percent from one week earlier

WASHINGTON, D.C. (October 28, 2026) — Mortgage applications increased 3.4 percent from one week earlier, according to data from the Mortgage Bankers Association’s (MBA) Weekly Mortgage Applications Survey for the week ending October 23, 2026.

The Market Composite Index, a measure of mortgage loan application volume, increased 3.4 percent on a seasonally adjusted basis from one week earlier. On an unadjusted basis, the Index increased 3 percent compared with the previous week. The Refinance Index increased 3 percent from the previous week and was 61 percent lower than the same week one year ago. The seasonally adjusted Purchase Index increased 4 percent from one week earlier. The unadjusted Purchase Index increased 3 percent compared with the previous week and was 18 percent lower than the same week one year ago.

“Mortgage rates declined for the second week in a row, with the 30-year fixed rate decreasing to 7.37 percent, the lowest in three weeks. The decline in rates gave borrowers some relief, with applications rebounding slightly, particularly conventional applications,” said Joel Kan, CMB, MBA’s Vice President and Deputy Chief Economist.

“Mortgage rates are still more than a percentage point higher than the same week last year and most homeowners still have rates much lower than prevailing market rates. The ARM share of applications increased to 11.3 percent, the highest level in more than a year, as more borrowers applied for ARM loans to lower their monthly payments.”

Added Kan, “While purchase applications increased over the week, they were 18 percent behind last year’s pace as many homebuyers have put their purchase plans on hold. Similarly, refinance applications were down more than 60 percent from a year ago, as most borrowers have little to gain from refinancing.”

The refinance share of mortgage activity decreased to 38.9 percent of total applications from 39.0 percent the previous week. The adjustable-rate mortgage (ARM) share of activity increased to 11.3 percent of total applications.

The FHA share of total applications increased to 16.6 percent from 16.3 percent the week prior. The VA share of total applications decreased to 11.0 percent from 11.5 percent the week prior. The USDA share of total applications remained unchanged at  0.5 percent from the week prior.

The average contract interest rate for 30-year fixed-rate mortgages with conforming loan balances ($832,750 or less) decreased to 7.37 percent from 7.41 percent, with points increasing to 0.76 from 0.75 (including the origination fee) for 80 percent loan-to-value ratio (LTV) loans. The effective rate decreased from last week.

The average contract interest rate for 30-year fixed-rate mortgages with jumbo loan balances (greater than $832,750) decreased to 7.28 percent from 7.33 percent, with points increasing to 0.64 from 0.60 (including the origination fee) for 80 percent LTV loans. The effective rate decreased from last week.

The average contract interest rate for 30-year fixed-rate mortgages backed by the FHA decreased to 7.12 percent from 7.13 percent, with points decreasing to 1.07 from 1.15 (including the origination fee) for 80 percent LTV loans.  The effective rate decreased from last week.

The average contract interest rate for 15-year fixed-rate mortgages decreased to 6.70 percent from 6.73 percent, with points increasing to 0.85 from 0.73 (including the origination fee) for 80 percent LTV loans. The effective rate remained unchanged from last week.

The average contract interest rate for 5/1 ARMs decreased to 6.41 percent from 6.46 percent, with points increasing to 1.20 from 1.11 (including the origination fee) for 80 percent LTV loans.  The effective rate decreased from last week.

The survey covers U.S. closed-end residential mortgage applications originated through retail and consumer direct channels. The survey has been conducted weekly since 1990. Respondents include mortgage bankers, commercial banks, thrifts, and credit unions. Base period and value for all indexes is March 16, 1990=100.

———————————————————–

Ann O’Rourke, MAI, SRA, MBA

Appraiser and Publisher Appraisal Today

1826 Clement Ave. Suite 203 Alameda, CA 94501

Phone: 510-865-8041

Email:  ann@appraisaltoday.com

Online: www.appraisaltoday.com

Posted in: appraisal business, Appraisal fees, appraisal how to, appraisal management company, Appraisal Software, Fannie, New URAR, UAD 3.6

ROAD to Housing Act and Appraisers

Newz: ROAD to Housing Act and Appraisers, UAD 3.6 Adjustments

October 23, 2026

ARTICLE LIST – In order, Scroll down the page to read.

  • LIA AD: Judicial Appraiser Panels: Balancing Opportunity and Liability
  • 21st Century ROAD to Housing Act By Jo Traut
  • 5 Moody Gothic Victorian Homes You Can Buy for Under $500K Right Now
  • I Wish the UAD 3.6 Deadline Would Hurry Up and Get Here, By Chad Barker
  • MY AD: Appraisal Forms Software in September, 1993
  • Surviving UAD 3.6: Secondary Market Risk Protocols, By Desiree Mehbod
  • UAD 3.6 Adjustments: New Rules, Same Principles, By Doug Smith
  • MY UAD 3.6 UPDATE – Where to get free appraisal webinars and podcasts on youtube. Demos of UAD 3.6 software and other relevant topics.
  • MBA Stats: Mortgage applications decreased 5.3 percent from one week earlier


Thanks to our Sponsor!!!

——————————————————————

21st Century ROAD to Housing Act

By Jo Traut

Excerpts:

What Is the 21st Century ROAD to Housing Act?

The 21st Century ROAD to Housing Act (Renewing Opportunity in the American Dream) became law on July 11, 2026. The legislation addresses a wide range of housing-related issues, including housing supply, affordability, consumer protections, and modernization efforts across several federal housing programs.

Appraisal-related provisions were included as part of broader efforts to improve the homebuying process and strengthen the appraisal profession.

Several provisions are particularly relevant to appraisers, from expanded FHA eligibility to workforce development initiatives and standardized reconsideration of value procedures.

What the New Law Means for Appraisers

For years, state-licensed residential appraisers have largely been excluded from FHA appraisal work. The 21st Century ROAD to Housing Act could eventually change that.

The new federal law includes several appraisal-related provisions designed to expand opportunities within the profession, modernize appraisal oversight, improve consumer protections, and support the development of the next generation of appraisers.

While some changes will require additional implementation and guidance before they take effect, appraisers should begin paying attention now, especially those interested in future FHA appraisal opportunities.

Here’s what appraisers need to know about the law, its potential impact on the profession, and how to prepare for what’s ahead.

Key Changes for Appraisers

• Licensed Appraisers May Once Again Be Eligible to Perform FHA Appraisals

• Trainee Appraisers Will Be Added to the ASC National Registry

• Grants Are Authorized for Appraiser Education and Workforce Development

• Reconsiderations of Value Receive a Federal Framework

• Appraisal Oversight and Registry Funding Are Updated

• A Public Appraisal Database Study Is Underway

How Appraisers Can Prepare Now

When Will These Changes Take Effect?

To read more, Click Here

My comments: If you do lender residential appraisals, read this full article. An excellent summary of what it means for appraisals. I have been following this topic for a long time. Finally it parts of it may be implemented over time. Be ready for when they come!


Read more!! →

Posted in: appraisal regulations, Appraisal Software, UAD 3.6

UAD 3.6 Fees for Appraisers

Newz: UAD 3.6 Fees, Fun Appraiser Game, Who Can Get Your Appraisal Data?

October 16, 2026

ARTICLE LIST – In order, Scroll down the page to read

  • LIA AD: Problem with An Affidavit
  • UAD 3.6 and the Appraisal Fee Chain: Who Actually Sets the Fee?, By Doug Smith, SRA
  • Lots Under Water
  • Certification 25: The 20-Year Fight Over Who Gets to Use Your Data, By Isaac Peck, WorkingRE, Publisher
  • Appraiser Game – Something FUN, By Dustin Harris
  • MY AD: 2026 E&O Update – Claims, Payment Options, Lawsuits, Etc
  • Inspectors Blocked the Door, Appraisers handed over the Keys By Desiree Mehbod
  • MBA STATS: Mortgage applications decreased 2.7 percent from one week earlier


Thanks to our Sponsor!!!

——————————————————-

UAD 3.6 and the Appraisal Fee Chain: Who Actually Sets the Fee?

By Doug Smith, SRA

“…the higgling and bargaining of the market…”

— Adam Smith, The Wealth of Nations, 1776

There has been considerable discussion about appraisal fees as UAD 3.6 is implemented. Much of the criticism over resistance to fee increases has been directed at Appraisal Management Companies.

But before deciding where responsibility lies, perhaps we need to follow what might be called the appraisal fee chain.

It begins with the borrower

A consumer seeking to purchase or refinance a residence provides information to a lender. The familiar conventional mortgage application is the Uniform Residential Loan Application (URLA), also known as Freddie Mac Form 65/Fannie Mae Form 1003.

For federal mortgage disclosure purposes, an application is considered received once the lender has six pieces of information: the consumer’s name, income, Social Security number, property address, estimated property value, and desired loan amount.

Once those items have been received, the lender generally must provide a Loan Estimate within three business days.

That Loan Estimate includes estimated loan and closing costs, including the anticipated cost of an appraisal when one is required.

This is where the appraisal fee chain gets interesting.

Federal disclosure rules limit how much certain estimated charges can increase between the Loan Estimate and closing. Depending on the circumstances, some required third-party service charges may be subject to a 10% cumulative tolerance, while others are subject to different rules. A valid changed circumstance may also permit a revised Loan Estimate.

So here is the first question:

Does the appraisal amount initially disclosed to the borrower influence the fee that can later be offered to the appraiser?

Once the borrower indicates an intent to proceed, the appraisal ordering process moves forward. Depending on the lender’s business model, the appraisal may be ordered directly from an appraiser or through an AMC.

Eventually, an assignment reaches an appraiser with a proposed fee.

But where in the appraisal fee chain was that number actually established?

Was it established by the lender when estimating the cost of the loan?

Was it established through an existing agreement or fee schedule between the lender and AMC?

Does the AMC determine the fee it offers the appraiser?

For lenders ordering directly, are they expecting UAD 3.6 assignments to be completed for the same fees previously paid for UAD 2.6 assignments?

And when an appraiser responds that the proposed fee is inadequate, how far back up the appraisal fee chain does that information travel?

These questions matter because UAD 3.6 changes the appraisal product and, for many appraisers, the process required to produce it. Appraisers are investing in training, software and equipment. Inspection procedures and data collection are changing. During the transition, the time required to complete an assignment may change as well.

Yet much of the current discussion seems to begin with the assumption that the appraisal fee should remain where it was.

Perhaps the question should not simply be, “Why won’t AMCs increase appraisal fees?”

The better question may be:

Where in the appraisal fee chain is the price of a UAD 3.6 appraisal actually being established—and is there still room for the market to establish a different price?

Nearly 250 years ago, Adam Smith described part of that price-setting process as the “higgling and bargaining of the market.”

Appraisers are participants in that market too.

A proposed fee is a proposal, not necessarily the market price.

Perhaps it is time for a little more higgling and bargaining.

My comments: I had never known about this before. Thanks to Doug Smith for the info!

Read more!! →

Posted in: appraisal business, Appraisal fees, E&O

For Appraisers: FHA Adopting UAD 3.6

Newz: FHA Adopting UAD 3.6, AO-41: Tech Guidance, Analysis of 2026 Appraisal Licenses, Certification 25 (in UAD 3.6)

October 9, 2026

ARTICLE LIST – Scroll down to see the articles, in order

  • LIA AD: “Off the cuff” opinions
  • FHA Announces Optional Broad Production Period for Uniform Appraisal Dataset (UAD) 3.6
  • Summary of Proposed Changes to HUD Handbook 4000.1 – September 2026
  • 8.5-Acre Waterfront Palm Beach Megamansion Owned by Billionaire Tech Mogul Is Listed for a Staggering $165 Million
  • (Advisory Opinion) AO-41: TAF’s New Tech Guidance and What It Means, By Isaac Peck, Publisher WorkingRE
  • MYAD: UAD 3.6 – A Phase-In Approach: Get the Report Done first By Doug Smith, SRA
  • Certification 25 and the Quiet Breach of Appraiser Confidentiality, By Desiree Mehbod, Part 1 and 2
  • Analysis of 2026 ASC Appraisal License Data By Chase Pursley
  • MY UAD 3.6 UPDATE – Exemption clarifications, Cert 25, VA
  • MBA STATS: Mortgage applications decreased 6.0 percent from one week earlier

FHA Announces Optional Broad Production Period for Uniform Appraisal Dataset (UAD) 3.6

FHA is pleased to announce a major step toward implementation of Uniform Appraisal Dataset (UAD) 3.6. Following the successful completion of beta testing, FHA’s Electronic Appraisal Delivery (EAD) portal is now available for an optional broad production period for mortgagees to submit appraisals using UAD 3.6.

This optional phase gives mortgagees flexibility to transition to UAD 3.6 for FHA cases prior to the government sponsored enterprises’ (GSEs’) mandatory transition scheduled for November 2, 2026.

What you need to know and do now:

Effective immediately, all FHA-approved mortgagees participating in Title II forward mortgage and Home Equity Conversion Mortgage (HECM) programs may begin submitting appraisals in the UAD 3.6 format.

Mortgagees may continue to deliver all or some of their appraisals to the EAD portal in the legacy UAD 2.6 format.

For a given case number, the same UAD format of the initial submission must be used in all subsequent appraisal submissions for that case ― submission of multiple formats is not permitted.

FHA will continue to gather information to assess mortgagee transition readiness before establishing and announcing an FHA mandatory adoption date.

Mortgagees and appraisers should review the UAD 3.6 Implementation Preparedness Toolbox resource, available on the EAD portal webpage, for key technical specifications and transition guidance.

To read the UAD 3.6 Implementation Preparedness Toolbox, Click Here

To read the announcement (pdf) , FHA INFO 2026-23, with more links,

My comment: Good to see what FHA is doing. For VA info, see MY UAD 3.6 UPDATE below

Read more!! →

Posted in: Appraisal Standards Board, Appraisal Subcomitee, Appraiser Survey, ASB Appraisal Standards Board, Fannie, FHA, GSEs

GSEs Create Exception for UAD 3.6 Deadline for Approved Lenders

Newz: GSEs Create Exception for UAD 3.6 Deadline for Approved Lenders Through May 19, 2027, Weather Impact on Appraisals

October 2, 2026

ARTICLE LIST – Scroll down the page to read

  • LIA AD: Weather Impact
  • GSEs Create Exception for UAD 3.6 Deadline for Approved Lenders Through May 19, 2027, Plus ACI Update, By Frank Andorka, Managing Editor, WorkingRE
  • Palm Beach’s Landmark ‘Ham and Cheese House’ Is Listed for an $105 Million
  • MY AD: Disciplinary Proceedings: What Conduct Leads to Discipline? By Claudia Gaglione
  • The Mathematics of Judgment By Dustin Harris
  • Fewer Appraisers. Better Appraisers. Which One Are You Going to Be? By Dustin Harris
  • MY UAD 3.6 UPDATE – ACI NEWS:Only the desk top version is withdrawn. The cloud base program still works.
  • 18th Annual Appraisal Summit in Las Vegas – Oct. 31-Nov. 3, 2026.

Hear what the GSEs say about Nov. 3. All the software vendors will be there – demos, questions. Network with appraisers.

HAVE FUN! OCTOBER 31 IS HALLOWEEN!!

  • MBA stats: Mortgage applications decreased 6.0 percent from one week earlier

———————————————————————

GSEs New Exception for UAD 3.6 Deadline for Approved Sellers : Runs through May 19, 2027
PLUS ACI UPDATE

By Frank Andorka, Managing Editor, WorkingRE

Approved sellers who are unable to fully implement UAD 3.6 before the formal Nov. 2, 2026, deadline will be allowed to continue submitting legacy UAD 2.6 appraisal reports through May 19, 2027, according to Fannie Mae and Freddie Mac.

The GSEs will also allow resubmissions of UAD 2.6 appraisal reports through June 27, 2027. As of March 1, 2027, UAD 2.6 appraisals will no longer qualify for certain appraisal-related representations and warranties relief.

From March 1 through May 19, 2027, UAD 2.6 reports will receive a Collateral Underwriter® (CU) risk score of 999 when submitted to Fannie Mae, and their functionality will be reduced in both CU and Loan Collateral Advisor®. The GSEs encourage sellers to fully adopt UAD 3.6 as soon as possible, as this is a one-time policy exception that will not be extended.

“Many lenders are submitting UAD 3.6 appraisal reports; however, some lenders may need more time to adopt,” the GSEs said in the release announcing the exception.

Submitting a UAD 2.6 report after Nov. 2 will require explicit approval from the GSEs. To request a policy exception, a representative of the seller who is authorized to enter into a binding contract must complete the online UAD 3.6 Policy Exception Request for each GSE to which it sells loans.

To read the GSE UAD 3.6 Policy Exception documents, Click Here

====================================

ACI Update

In a perhaps unrelated announcement the day before (September 29, 2026) the GSEs announcement, ACI, an appraisal software that has been serving appraisers for decades, signaled that they were scrapping ACI Sky™ Workbench, it’s UAD 3.6-compliant appraisal report.

ACI wrote on its Facebook page:

“After careful consideration, we’ve made the decision to stop the current version of ACI Sky™ Workbench and focus our efforts on developing a significantly improved Workbench 2.0 experience, targeted for release in Spring 2027…. Access to the current ACI Sky Workbench platform will end October 9, 2026.”

Appraisers in the comments on ACI’s post reported they had been in communication with ACI and were told that “there was no interim solution in place for current ACI subscribers for completing UAD 3.6 assignments,” according to one appraiser. That same appraiser quoted an email he received as saying: “At this time, the information provided to us confirms that ACI Desktop will remain available for existing UAD 2.6 and legacy workflows, but it does not provide a confirmed interim ACI workflow for completing UAD 3.6 reports after Workbench is removed.”

To read the full WorkingRE article, Click Here

My comments on Exceptions:

THIS DOES NOT CHANGE THE NOVEMBER 2, 2026 DATE FOR ALL SELLERS/ LENDERS (WITHOUT APPROVED EXCEPTIONS) TO ONLY SUBMIT UAD 3.6 APPRAISALS.

I read an online post from an appraiser about using prediction markets like Kalshi and Polymarket for The UAD 3.6 deadline of November 2. The post had several interesting comments posted.

My opinion has been No Change for November 2 for awhile. The GSEs have seen successful appraisal and lender submissions for awhile. Now they have a way to keep the deadline with one exception.

I am not surprised. I have known for a long time that the “weak link” is the lenders not the appraisers. Appraisers just have to learn how to do the changes in reporting. Lenders have to redo their computer systems for all the changes.

I attended two event sessions where GSE representatives were speaking. I asked them about what was happening with lenders. They did not say much.

I was available to find very little help for lenders online.

What appraisers need to do – a few ideas

Learn about the new Exceptions and what is required. It is complicated.

To read the GSE UAD 3.6 Policy Exception documents, Click Here

When a lender requests an appraisal be sure you both agree on what type of appraisal will be needed: UAD 3.6 or 2.6. Get the request in writing.

To be sure, you could ask if they have an approved Exception. Then you will know they will be submitting a UAD 2.6 appraisal.

A few ideas from Doug Smith

1. Keep training on 3.6. The exception postpones the deadline for some lenders. It doesn’t retire the format.

2. Get the format in writing. On every order after Nov 2, confirm 2.6 or 3.6 in the engagement letter, especially for FHA and VA.

3. Ask lender clients whether they’ve requested the exception from one GSE, both, or neither.

4. Expect a dual-track transition. Some clients will still order 2.6 into 2027. Others will move early to avoid the March 1 penalties.

Status of FHA and VA – unknown currently. Lots of rumors and comments.

In future Friday newsletters I will let you know more, as it becomes available. It is complicated. I received notification of these new exceptions on September 30, 2026. I had limited research time available before my newsletter deadline on October 2, 2026 at 6:30 AM.

Many thanks to WorkingRE for writing this article on November 2026 about the new GSE Exception changes and ACI update!

Read more!! →

Posted in: adjustments, GSEs, state appraiser regulators, UAD 3.6

New Fannie Highest and Best Use Playbook

Newz: New Fannie Highest and Best Use Playbook, UAD 3.6 Nov. 2 and Other Deadlines??

September, 25, 2026

ARTICLE LIST:

In Order, Scroll down the page to read

  • LIA AD: Conflicting Assignments and Professional Ethics
  • New Fannie Highest and Best Use Playbook and Q&As
  • For the Price of a San Francisco Condo, You Can Buy a 400-Acre Historic Marshland Retreat
  • UAD 3.6 — Whose November 2 Deadline Is It? There are many dates!! By Doug Smith, SRA
  • MY AD: Make use of your driving time by exercising
  • Rethinking Private Appraisal Delivery: Building Interactive Web Reports with AI By Dustin Harris
  • MBA stats: Mortgage applications decreased 1.5 percent from one week earlier


Thanks to our Sponsor!!!

Very reasonable prices and good open rates for our ads!

————————————————————

New Fannie Highest and Best Use Playbook and Q&As

By Dave Towne

For those of you doing (or will do) the New URAR/UAD 3.6 mortgage lending reports from now into the future, you need to read and understand this new policy change from FannieMae. Because this new UAD report process also applies to FreddieMac, my presumption is they will issue a policy statement of their own with similar wording.

For the time being, here is the FNMA new policy, issued on Sept. 2, 2026: Highest and best use requirements for Uniform Appraisal Dataset (UAD) 3.6

This policy updates the highest and best use requirements for appraisal reports completed using Uniform Appraisal Dataset (UAD) 3.6.

These changes apply only to UAD 3.6 appraisal assignments to support the new Uniform Residential Appraisal Report (URAR) reporting requirements and do not apply to appraisal reports completed using legacy appraisal report forms.

We updated our policy to:

• require the property’s highest and best use, as improved or as proposed, to be a residential use, rather than requiring it to be the property’s present use;

• define present use, residential use, and subordinate use in the context of highest and best use;

• require the property to be a primarily residential one- to four-unit property, with any non-residential use subordinate to the residential use, replacing the previous “residential in nature” guidance; and

• establish the eligibility criteria and reporting requirements for one- to four-unit residential properties when the present use does not satisfy one or more of the highest and best use tests.

The UAD 3.6 Policy Supplement has been updated to reflect these changes.

Effective: This policy change is effective immediately for appraisal reports completed using UAD 3.6.

Remember, to be USPAP compliant, you can’t “just check the box” on the New URAR/UAD 3.6 data base input field (or on the Legacy forms either) to indicate ‘present use,’ and then move on. You must add a written statement in that site section comment input field explaining why you decided that is the accurate use of the property. Craft your statement to comply with the above policy.

Also remember this: if you decide the property’s H&BU is not Residential use, you must check the box “No.” In most cases, when you do that, the need to complete a full appraisal report ends at that point because the lender cannot proceed with a residential mortgage loan. Your statement needs to define what the actual use is if not Residential. Stop working on the report and contact your client to fully explain the current situation. Let them determine how to proceed.

—————————————————————–

What is in Fannie’s New The Highest & Best Use 25 page Playbook (Per Fannie)

• This playbook provides key concepts and illustrative scenarios to help industry participants better understand how the results of the highest and best use (HBU) may affect loan eligibility.

• Each scenario presents a complex highest and best use question based on the specific circumstances of a subject property. While every property has its own unique characteristics and circumstances, which may lead to different conclusions, these scenarios are designed to demonstrate how you can apply Fannie Mae policy consistently across a range of situations. They are intended to provide practical guidance and support informed, policy-compliant decision-making.

• A resolution is provided for each scenario, along with the appraiser and lender responsibilities with relevant Fannie Mae Selling Guide Supplement: Uniform Appraisal Data (UAD) 3.6 Policy resources.

• The Highest and Best Use Frequently Asked Questions document addresses common questions related to present use, highest and best use, mixed-use properties, analysis of subordinate uses, comparable sales, the URAR, and loan eligibility. The document is available separately and linked throughout the Playbook for easy reference.

To read the Highest and Best Use Playbook, Click Here

To read the separate FAQ document, with 27 Q&As, Click Here

My comments: Many thanks (again) to Dave Towne for writing a summary of the 25 page document at the top of this article. To subscribe to his regular emails, send an email to dtowne@fidalgo.net . Say that you want to subscribe to his list. I have been subscribing for many years.


Read more!! →

Posted in: AI, appraisal, appraisal how to, Fannie

UAD 3.6 — Whose November 2 Deadline Is It?

UAD 3.6 — Whose November 2 Deadline Is It?

By Doug Smith, SRA

There may be an important misunderstanding about the November 2, 2026 UAD 3.6 mandate.

November 2 is not the deadline for the appraiser to deliver a UAD 2.6 appraisal to the lender or AMC. It is the deadline for a new UAD 2.6 appraisal to have already made its initial submission to UCDP.

That distinction matters.

An appraiser could complete a legacy UAD 2.6 appraisal before November 2 and deliver it to the client before November 2—and it could still be too late. If its initial submission to UCDP occurs on or after November 2, UCDP will return a Fatal message and a “Not Successful” status.

The GSE transition timeline provides a remarkably clear example. A UAD 2.6 appraisal is ordered on October 1. It is not initially submitted to UCDP until November 5. The result: Not Successful. The timeline states that UAD 2.6 appraisals must be submitted to UCDP before the mandate or converted to UAD 3.6.

So an appraiser looking at November 2 as “the last day I can finish a legacy appraisal” is looking at the wrong date.

The appraiser’s practical deadline has to be earlier.

The GSEs recognize this. Their guidance tells lenders to allow enough time to order, receive and submit remaining UAD 2.6 reports before November 2. They are also encouraging lenders to begin ordering UAD 3.6 reports before the mandate.

What Happens to a Report Caught in the Pipeline?

Suppose an appraiser accepts a UAD 2.6 assignment in October, inspects the property, completes the appraisal and delivers it to the lender before November 2. For whatever reason, however, its initial UCDP submission does not occur until after the mandate.

The GSE timeline says the UAD 2.6 appraisal must have been submitted before the mandate or converted to UAD 3.6.

That word “converted” deserves some thought.

What does conversion mean to an appraiser who has already inspected the property, collected the data, completed the analysis and delivered a legacy report? Does the appraiser have all the information required by UAD 3.6? Would another inspection be necessary because information required for the new report was not collected during the original inspection? How much can the software actually convert? How much additional work will be required? And who will be responsible for the additional time and fee?

Those are questions better considered before accepting the assignment than after a completed UAD 2.6 appraisal has missed the UCDP deadline.

There is also an important distinction. If the initial UAD 2.6 appraisal was successfully submitted to UCDP before November 2, later revisions can continue in UAD 2.6 using the existing Document File ID during the transition period.

But the Road Is Still Under Construction

Yes, appraisal software continues to be a road under construction. But the appraisal profession has repeatedly proven its resiliency.

Now is the time to seek out workable solutions, rely on the ingenuity of innovation, and make the best use of the tools we have under admittedly challenging circumstances.

The November 2 mandate is approaching whether every software feature is finished or not.

Perhaps It Is Time for Appraisers to Take the Lead

From this point forward, perhaps one simple question should become part of accepting a residential appraisal assignment:

“Is this appraisal intended for submission to UCDP?”

If the answer is yes, perhaps the next question should be:

“Should this assignment be completed using UAD 3.6 rather than the legacy UAD 2.6 format?”

That does not mean the appraiser unilaterally changes the client’s reporting requirements. It means the appraiser raises the question while the assignment conditions and reporting requirements can still be clarified—rather than after the appraisal has been completed.

Not every residential appraisal is headed to UCDP, which is precisely why the first question is important.

For appraisers already completing and delivering UAD 3.6 reports, the transition is already underway. For those who have chosen to sit it out until the mandate, the published requirements now make clear what November 2 actually means.

Perhaps the most important group is somewhere in between—appraisers who have trained, experimented with 3.6, or are preparing for it, but continue to accept most assignments in 2.6.

For that group, the next several weeks may be critical.

Both UAD 2.6 and UAD 3.6 can currently move through the transition process. On November 2, that choice ends for new UCDP submissions.

Perhaps our transition date should not be November 2. Perhaps our transition should begin now, one assignment at a time.


Posted in: Uncategorized

Artificial Intelligence Will Not Replace Appraisers

Newz: Freddie ADU Guide, AMCs, AI and Appraisal Photos, FHA QC Changes

September 18, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Expanding Intended Users? Not So Fast
  • A Practical Guide to Appraising Accessory Dwelling Units (ADUs) By Freddie Mac
  • Artificial Intelligence Will Not Replace Appraisers By Tony Pistilli
  • Former 1847 Ohio Jail Goes Under Offer for $400K: How One Family Turned Inmate Cells Into Pantries and Closets
  • MY AD: The Appraisal Triangle: Knowledge. Expe